 RESEARCHOpen ThesisMemo
Start with the price bridge
Advanced Drainage Systems announced an agreement on October 5 to acquire StormTrap. For shareholders in NYSE-listed WMS, the headline valuation requires a careful bridge: the approximately 10 times multiple includes both expected tax benefits and expected cost synergies. It is not simply the announced purchase price divided by the target’s historical earnings.
The SEC filing describes an agreement signed October 1 to acquire all equity interests in StormTrap Investments and its direct subsidiaries. The approximately $530 million price becomes approximately $450 million after adjusting for the present value of expected tax benefits, with purchase-price adjustments still applicable. Funding is expected from cash on hand and the existing credit facility.
Those figures answer different questions. The nominal price describes the transaction before the expected tax benefit. The adjusted figure credits a future economic benefit today. Neither should be silently substituted for the other when comparing this deal with acquisitions whose quoted multiples use different conventions.
Three multiples, three different assumptions
The acquisition release reports approximately $165 million of revenue and $40 million of adjusted EBITDA for the twelve months ended July 2026. Using those rounded disclosures, $530 million divided by $40 million equals approximately 13.25 times. Using $450 million instead gives approximately 11.25 times. These are our arithmetic comparisons, not additional valuation multiples reported by ADS.
The company’s approximately 10 times figure also includes expected run-rate cost synergies. That makes it a forward-looking, synergy-adjusted comparison. Historical adjusted EBITDA and earnings after anticipated integration savings are not interchangeable denominators. The difference matters even if management ultimately delivers all the expected benefits.
The $80 million difference between the two price figures is likewise an implied present-value adjustment calculated from rounded disclosures. It should not be described as an $80 million cash rebate at closing. Timing and realization matter when converting future tax benefits into economic value.
Investors should also avoid solving backward from the rounded 10 times headline to assert an exact, undisclosed synergy target. Rounded inputs and potentially different valuation conventions cannot support that precision. A useful model would keep nominal consideration, expected tax benefits, historical adjusted EBITDA and anticipated savings in separate rows.
Continue your research with ThesisMemo.
See how ThesisMemo works Explore the product · Start with a free research previewThe product fit runs through project specifications
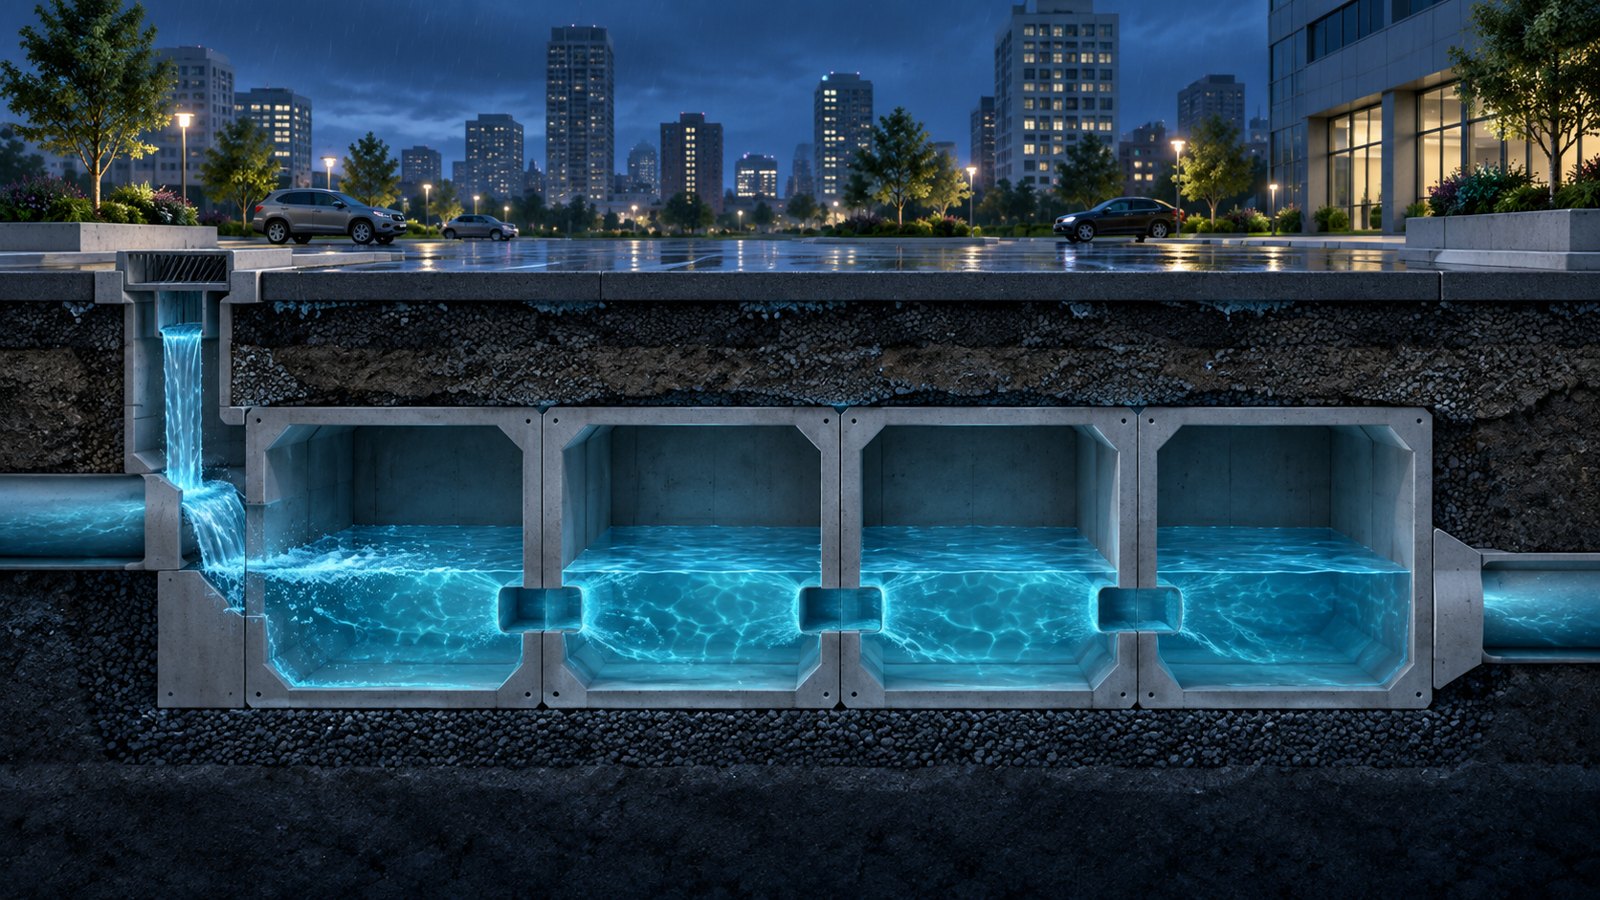
StormTrap’s own solutions page describes stormwater detention, infiltration, treatment and related applications. Detention manages runoff volume and discharge timing; infiltration moves water into native soil. Those functions help explain why the strategic question extends beyond adding another product to a distribution catalog.
The company also describes work with customers through planning, design, approval and construction, including design and budget assistance. In that setting, getting a system specified for a project can matter before a purchasing decision. Product suitability, local requirements and engineering relationships can influence whether a broader sales offering becomes an actual order.
For ADS, the analytical opportunity is to turn an expanded stormwater offering into projects it could not previously serve as effectively. The risk is assuming that product fit alone guarantees incremental sales. A specification opportunity is not backlog, and a larger addressable set of projects is not recognized revenue.
Evidence of success would include adoption of the combined offering, reliable project execution and cash generation after the associated costs. Without such evidence, cross-selling remains a plausible mechanism rather than a demonstrated return on the acquisition price.
Accretion and completion are separate tests
ADS expects the transaction to be accretive to adjusted earnings per share in its first year. That is a management forecast using an adjusted measure. It does not by itself establish a GAAP earnings outcome, an attractive return on invested capital or the realization of the valuation assumptions.
The expected closing is in the fourth calendar quarter of 2026, subject to regulatory approvals and other customary conditions. Board approval and a signed agreement do not mean ownership has already transferred. Until completion, the financing and operating case should be discussed as proposed rather than realized.
The next useful disclosures are confirmation of closing, the final purchase-price allocation, financing details and a clearer bridge between historical earnings and expected savings. After closing, compare actual cash generation and integration costs with the original economic case. A stronger investment argument would show that benefits materialize without offsetting costs; a weaker one would emerge if timing, savings or operating performance falls short.
The disciplined comparison is therefore not simply whether 10 times sounds inexpensive. It is whether the underlying cash commitment earns an acceptable return when tax benefits and operating improvements are tested separately.
Turn your next headline into a better research question.
Discover a workspace for company research, market context, news and original filings. See how ThesisMemo fits into your research process.
See how ThesisMemo works Explore the product · Start with a free research preview- ADS October 5 Form 8-K: definitive agreement ↗
- ADS acquisition release filed as Exhibit 99.1 ↗
- StormTrap official stormwater solutions ↗
Research and education, not personalized investment advice. Facts and examples should be read in the context of their stated periods. Follow the original disclosures for the complete record.